
Where Will Tractor Supply Stock Be in 3 Years?
Tractor Supply (NASDAQ: TSCO) is an interesting retailer, given that it leans heavily on its farm theme. But its customer base isn't farmers, or at least not exclusively farmers. The ability to attract a broad customer base allowed the company to grow at a rapid clip for many years. There's no sign that this trend will stop over the next three years.
Tractor Supply is a glorified hardware store
If you have ever been to a Tractor Supply store, the focus on "farming" will likely have been very apparent. But step back from the obvious (including live chicks) and look at the whole store. It is more like a hardware store. That's important because there are only a fairly small number of professional farmers in the U.S., and they likely shop at even more specialized retailers.
Tractor Supply is geared toward hobby farmers and the general public. It's an important element of the model since it provides a lot more growth potential (the company is even branching out into a pet-focused version of its format called Petsense by Tractor Supply).

Image source: Getty Images.
At the end of the second quarter, the retailer had 2,181 stores. At the end of 2017, roughly five years ago, it had 1,685 stores, so there's been material store count growth in recent years. The company believes it can get to 3,000 stores. That means there's the potential for more store count growth ahead.
That's what investors should expect of Tractor Supply over the next three years: More stores that will lead to more sales revenue. Growth is still the story. The pace should pick up, as well, with management aiming for a run rate of 90 new stores a year by 2025.
Is Tractor Supply worth buying?
Growth is great, but you have to balance price versus value here. Paying too much for even a great company can still be a bad investment. Luckily, Tractor Supply doesn't appear to be overpriced, at least relative to its own history.
For example, the price-to-sales ratio of about 1.5 times is below the five-year average of 1.7 times. And the price-to-earnings (P/E) ratio of 19.8 times is below the longer-term average of 23.3 times or so. In this way, investors appear to have an opportunity to buy the stock at a price point that is historically attractive.
That valuation comes thanks to a roughly 20% decline in the stock price from recent peaks. The stock has fallen 40% or more multiple times, however, so the valuation could get even cheaper before there's a rebound in the stock price. In other words, if you buy today, be prepared for the possibility that things could get worse before they get better. That remains true even if the company executes well on its store expansion plans.
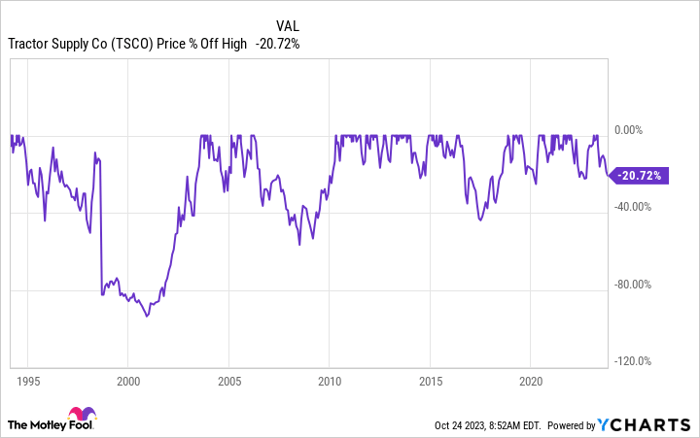
It's also worth noting that Tractor Supply's P/E ratio is above the level of both Home Depot and Lowes. So Tractor Supply may be cheap relative to its own history, but perhaps it isn't cheap relative to competitors. Still, given its growth plans, a higher valuation may be appropriate. But deep value investors probably won't find the company compelling.
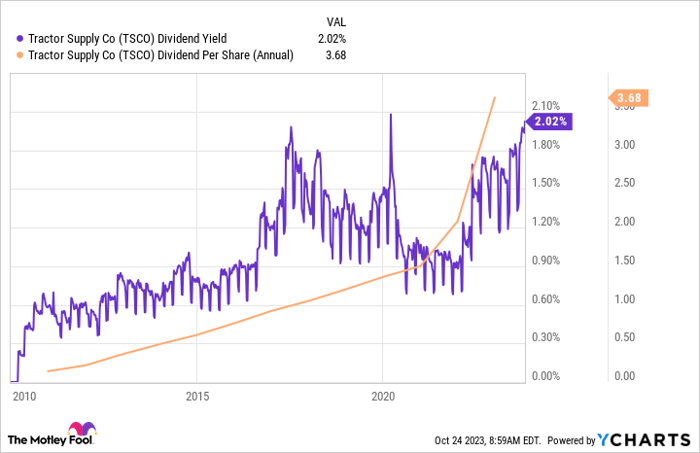
TSCO Dividend Yield data by YCharts
That said, dividend growth investors might also find the 2% or so dividend yield compelling here. It is at the high end of the company's historical yield range, and the dividend has grown consistently over time (14 years and counting at this point). Even more notably, the dividend growth rate over the past decade was a massive 25% a year on an annualized basis. That kind of dividend growth may, in fact, be worth paying up for.
Not a slam-dunk investment
Tractor Supply is a very interesting stock, but there are some trade-offs investors need to consider. It seems fairly clear that the company will be larger in three years' time, which is good. And the current pullback in the stock has brought valuations down to more attractive levels, including boosting the dividend yield toward historic highs.
But given the stock price history, the drawdown could have more room to run, and Tractor Supply isn't exactly cheap relative to competitors. Still, for long-term dividend growth investors willing to ride out near-term stock volatility, this could be an attractive time for a deep dive.
10 stocks we like better than Tractor Supply
When our analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Tractor Supply wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of October 23, 2023
Reuben Gregg Brewer has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Home Depot. The Motley Fool recommends Lowes and Tractor Supply. The Motley Fool has a disclosure policy.
