
Where Will ChargePoint Be in 10 Years?
Shares of ChargePoint (NYSE: CHPT) have declined since their peak in late 2020 and may now be reaching a value point if the operating results turn around. The $750 million market cap and 2023 revenue of $506.6 million puts the price-to-sales multiple at just 1.5 times, the lowest level since the company came public.
The challenge over the next decade is making money. ChargePoint hasn't been able to do that, and 2024 will be a critical year for the company.
Image source: Getty Images.
The razor/razor blade model falls flat
ChargePoint's strategy has long been to grow its installed base of chargers and make high-margin subscription revenue that grows as electric vehicle (EV) adoption increases. But that strategy has turned out to be flawed.
The sale of EV chargers, or Networked Charging Systems, is ChargePoint's primary source of revenue -- and that's a problem because it's a money-losing endeavor so far. In 2023, the company generated $360.8 million in revenue from chargers and spent $386.1 million to build them. On top of the losses, revenue was down 1%, so this hasn't been a great business.
Subscription revenue was up 41.2% to $120.4 million, and the gross margin was a fairly impressive 39%. But that came nowhere near enough to cover $480.1 million in operating expenses, which is why the company had a $457.6 million loss for the year.
Without major changes, ChargePoint won't last another decade.
Management's optimistic tone
In the fourth-quarter 2023 earnings report, management was confident they could reach non-GAAP adjusted EBITDA breakeven by the end of 2024. This compares to a loss of $45.3 million in Q4 2023 and $272.7 million for the whole year.
Some trends will make that challenging. First, U.S. automakers are moving to the NACS charging standard, further commoditizing chargers. Second, EV sales growth is slowing, and 2024 may be a year when buyers and manufacturers pull back. That's not a good environment for charger demand.
Looking a decade out
For ChargePoint to survive, it needs to start making money by selling chargers. The subscription business is nice, but chargers are the core business, and they have to be profitable to survive.
Operating expenses also need to be much lower to reach profitability. Right now, operating expenses are nearly equal to sales and should be more like 15% or 20% of sales for a hardware company.
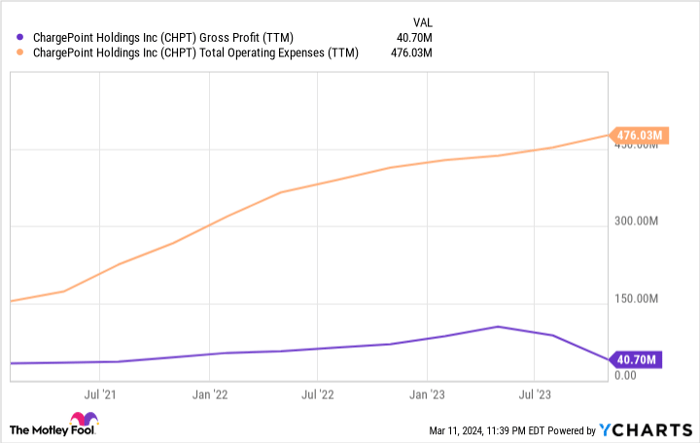
CHPT Gross Profit (TTM) data by YCharts
The fundamental problem is the competitive nature of EV chargers. They're effectively the same regardless of manufacturer, making it tough for ChargePoint to make much margin.
To make matters worse, the industry is coalescing around NACS, which means the charger will be the same for all manufacturers. How do you differentiate in that environment?
I think the future for ChargePoint is bleak given these competitive dynamics. The company has $327.4 million in cash, similar to the $328.9 million in operating cash burned in 2023. As the stock falls, offerings like the $287.2 million raised in 2023 will be harder to pull off.
Without a sale to another charger company, automaker, or utility, I don't see how ChargePoint will survive as a stand-alone company. That's the harsh reality for charger companies today.
Should you invest $1,000 in ChargePoint right now?
Before you buy stock in ChargePoint, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and ChargePoint wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Stock Advisor provides investors with an easy-to-follow blueprint for success, including guidance on building a portfolio, regular updates from analysts, and two new stock picks each month. The Stock Advisor service has more than tripled the return of S&P 500 since 2002*.
*Stock Advisor returns as of March 11, 2024
Travis Hoium has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
