
This 1 Chart Illustrates a Key Problem for Disney+
Kudos to Walt Disney (NYSE: DIS). The company's Disney+ net subscriber growth slowed to a scant 2.1 million households during its fiscal 2021 fourth quarter (ended Oct. 2, 2021), calling the media giant's early streaming customer targets into question.
Disney reaccelerated adoption of its flagship platform for the fiscal 2022 first quarter ended on Jan. 1, though, picking up 11.7 million paying customers since the previous quarter. Its other streaming services, Hulu and ESPN+, also saw net subscriber gains, putting the company's initial calls for between 230 million and 260 million active streaming subscriptions by the end of 2024 back on the table.
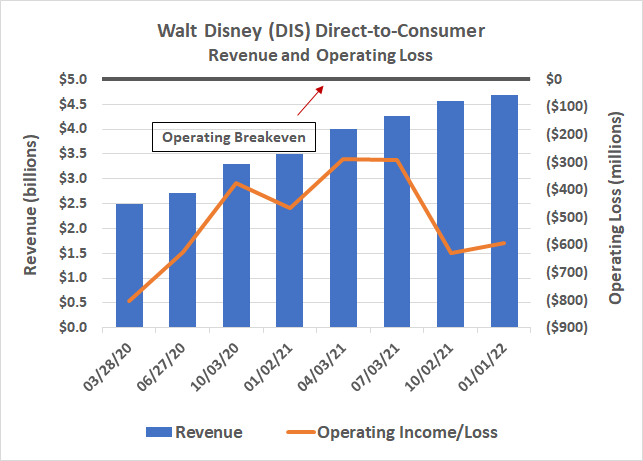
Before getting too comfortable with the idea that Walt Disney's streaming dreams are all coming true, however, know there's one lingering, glaring problem. This direct-to-consumer operation is still bleeding a lot of money with no clear picture as to how it may ever get out of the red and into the black.
Elusive profits
The good news: Disney's direct-to-consumer (streaming) revenue rolled in at $4.7 billion in the most recent quarter. That's up 34% on a year-over-year basis.
The bad news: Walt Disney's streaming operation lost $593 million in the same period. That's a 27% bigger loss than the company reported for this division in the prior-year quarter.
Image source: Getty Images.
Had the quarterly loss been an isolated incident, it might be something investors can overlook. Disney+ is a relatively young enterprise, and losses are expected as the business gets up to speed. But it has been in business for two years now, and there's not even a hint of fiscal viability yet.
Data source: Walt Disney. Chart by author.
Some will argue two years isn't enough time before passing judgment on how a business will stack up and shake out. And that argument holds some water. The company is only a little more than halfway to its 2024 streaming subscriber goal. More paying customers means more revenue to cover content production costs, and price increases may help boost profit margins as well.
The argument looks past one key reality, however. That is, Disney has yet to really open up its content wallet the way it says it's eventually going to. In late 2020, the company confirmed there were ten Marvel productions as well as ten Star Wars productions in the works, most of which have yet to begin production.
Subscriber growth may well lead to much-needed revenue growth but with plans to spend $33 billion on entertainment content this year alone -- for streaming and non-streaming purposes -- concerns are merited. Even if 245 million households are paying an average of $6.00 per month per subscription, that's still less than $18 billion worth of annual streaming revenue.
Also note that overall streaming revenue growth seems to be slowing.
Time for tougher questions
None of this is to suggest Disney is a lost cause. Cable television and movie revenue are still on the table, as are theme park and resort revenue. While the lion's share of the $33 billion earmarked for content will go to Disney+ and sports programming, the company's ultimately got several ways to monetize its products and generate a net return on its investments.
As it stands right now, though, the streaming math doesn't leave Disney's bulls with a lot to work with. Either spending plans will need to be reined in, or price increases need to be imposed, both of which discourage subscriber growth. At the very least, we're now deep enough into Disney's days as a streaming player for investors to start asking tougher questions, like when and how this is all going to start paying off.
10 stocks we like better than Walt Disney
When our award-winning analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Walt Disney wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of January 20, 2022
James Brumley has no position in any of the stocks mentioned. The Motley Fool owns and recommends Walt Disney. The Motley Fool recommends the following options: long January 2024 $145 calls on Walt Disney and short January 2024 $155 calls on Walt Disney. The Motley Fool has a disclosure policy.
