
Take-Two Interactive Stock: Bear vs. Bull
Take-Two Interactive (NASDAQ: TTWO) recently gave investors a lot to think about. The video game giant said in its Q3 earnings update that sales trends are weakening in the mobile-gaming niche that executives had bet on so aggressively in the past year. Take-Two is also delaying a few title launches into 2023.
However, its gaming portfolio has never been stronger, and Take-Two still has a huge audience of engaged users who are likely to continue playing in its ecosystem as the digital entertainment industry expands. With that big picture in mind, let's look at the main bear and bull arguments around the stock.
The bear case
Take-Two might not be done issuing surprisingly bad news. The company's early-November earnings report sparked a stock-price decline after management reduced their 2022 sales outlook while blaming the mobile division, along with slowing economic-growth trends. These factors could get worse before they get better.
The digital-advertising market is on track to slow even further in Q4. Take-Two might see weaker demand in console and PC game titles, too, compared to soaring growth a year ago. And its Zynga purchase, which cost about $12 billion, might bring extra integration and profitability challenges in a selling environment characterized by slow growth and cautious consumers.
The short-term industry outlook has changed a lot since Take-Two closed its Zynga acquisition in early 2022. But it still paid the price it negotiated back when growth seemed unstoppable.
The bull case
Management believes the current sales slowdown is just a temporary speed bump. "We have great confidence that, over the long term, our portfolio is poised to benefit from the significant expected growth in mobile gaming," CFO Lainie Goldstein said during a call with investors.
The portfolio is diverse enough that it can grow even if that niche underperforms for a while. Take-Two has a packed pipeline of content on the way over the next few fiscal years from brands like Grand Theft Auto, Red Dead Redemption, and its 2K sports franchises.
Meanwhile, consumers are still happily shifting their spending toward more recurring services, like season passes. This move is lifting Take-Two's cash flow and making the business perform more like a software-as-a-service business. It will likely make sales less susceptible to one bad game launch, too.
The stock is also much cheaper today, as investors price in the possibility of more growth downgrades in 2023. You can own Take-Two for 3 times sales right now, compared to 5 times sales for Electronic Arts and Microsoft's profit-to-sales ratio of 9.
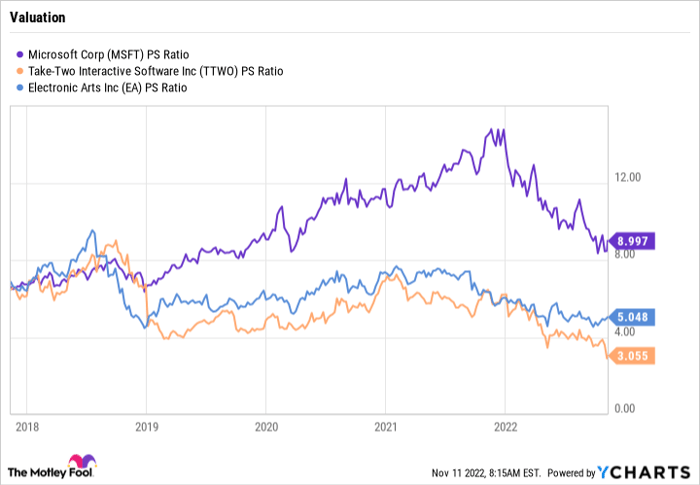
MSFT PS Ratio data by YCharts.
Take-Two doesn't have as bright of an outlook as these industry rivals right now. But investors willing to hold through volatility might be rewarded with market-thumping returns once the video-game niche returns to solid growth.
If you'd prefer more clarity, though, you might want to keep the stock on your watch list for another quarter or so. By early 2023, investors will have a better reading on the industry and know whether the Zynga acquisition tipped Take-Two into needing more drastic cost cuts or reorganization moves.
A scenario like that might make the next fiscal year a tough one for shareholder returns, even if the company is likely to recover over the long term.
10 stocks we like better than Take-Two Interactive
When our award-winning analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Take-Two Interactive wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of November 7, 2022
Demitri Kalogeropoulos has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Microsoft and Take-Two Interactive. The Motley Fool recommends Electronic Arts and recommends the following options: long January 2023 $115 calls on Take-Two Interactive. The Motley Fool has a disclosure policy.
