
Is XpresSpa Group (NASDAQ:XSPA) Using Too Much Debt?
Warren Buffett famously said, 'Volatility is far from synonymous with risk.' When we think about how risky a company is, we always like to look at its use of debt, since debt overload can lead to ruin. As with many other companies XpresSpa Group, Inc. (NASDAQ:XSPA) makes use of debt. But the real question is whether this debt is making the company risky.
What Risk Does Debt Bring?
Generally speaking, debt only becomes a real problem when a company can't easily pay it off, either by raising capital or with its own cash flow. In the worst case scenario, a company can go bankrupt if it cannot pay its creditors. However, a more usual (but still expensive) situation is where a company must dilute shareholders at a cheap share price simply to get debt under control. Of course, the upside of debt is that it often represents cheap capital, especially when it replaces dilution in a company with the ability to reinvest at high rates of return. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
What Is XpresSpa Group's Net Debt?
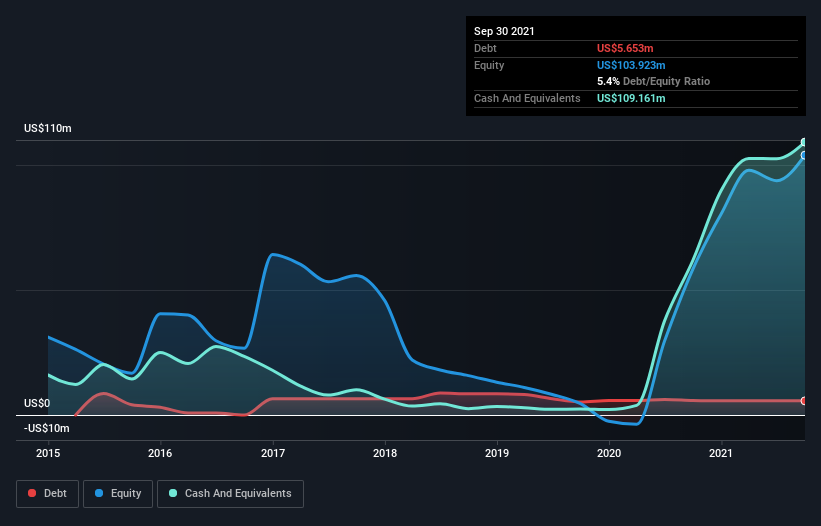
The chart below, which you can click on for greater detail, shows that XpresSpa Group had US$5.65m in debt in September 2021; about the same as the year before. However, it does have US$109.2m in cash offsetting this, leading to net cash of US$103.5m.
How Healthy Is XpresSpa Group's Balance Sheet?
Zooming in on the latest balance sheet data, we can see that XpresSpa Group had liabilities of US$17.2m due within 12 months and liabilities of US$8.16m due beyond that. Offsetting these obligations, it had cash of US$109.2m as well as receivables valued at US$64.0k due within 12 months. So it can boast US$83.9m more liquid assets than total liabilities.
This surplus liquidity suggests that XpresSpa Group's balance sheet could take a hit just as well as Homer Simpson's head can take a punch. Having regard to this fact, we think its balance sheet is as strong as an ox. Succinctly put, XpresSpa Group boasts net cash, so it's fair to say it does not have a heavy debt load! The balance sheet is clearly the area to focus on when you are analysing debt. But it is future earnings, more than anything, that will determine XpresSpa Group's ability to maintain a healthy balance sheet going forward. So if you want to see what the professionals think, you might find this free report on analyst profit forecasts to be interesting.
Over 12 months, XpresSpa Group reported revenue of US$45m, which is a gain of 151%, although it did not report any earnings before interest and tax. So there's no doubt that shareholders are cheering for growth
So How Risky Is XpresSpa Group?
We have no doubt that loss making companies are, in general, riskier than profitable ones. And we do note that XpresSpa Group had an earnings before interest and tax (EBIT) loss, over the last year. Indeed, in that time it burnt through US$7.8m of cash and made a loss of US$17m. With only US$103.5m on the balance sheet, it would appear that its going to need to raise capital again soon. Importantly, XpresSpa Group's revenue growth is hot to trot. While unprofitable companies can be risky, they can also grow hard and fast in those pre-profit years. There's no doubt that we learn most about debt from the balance sheet. But ultimately, every company can contain risks that exist outside of the balance sheet. We've identified 3 warning signs with XpresSpa Group (at least 1 which doesn't sit too well with us) , and understanding them should be part of your investment process.
At the end of the day, it's often better to focus on companies that are free from net debt. You can access our special list of such companies (all with a track record of profit growth). It's free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
