
Is Visa Stock a Buy?
Visa (NYSE: V) is the world's leading payments processing network, servicing over 200 countries and handling more than $14.3 trillion in payment volume in the 12 months ending on March 31. Through its extensive reach and brand recognition, Visa has become a household name and quintessential blue chip stock.
Few people would argue that it isn't a great business. But being a great business doesn't make a stock a no-brainer investment. Does that apply to Visa? Let's see.
Competitors won't catch up to its reach anytime soon
When it comes to businesses you can feel comfortable holding for the long term, a lot comes down to their competitive moat. Without it, a company's longevity is consistently at risk, since it could struggle to hold on to its market position and profitability in the face of increased competition.
In Visa's case, its competitive moat is its vast reach. At the end of 2022, Visa has over 100 million merchant locations, almost 40 million more than just a few years ago.
If you own an American Express or Discover credit card, there's a good chance you have run into a merchant, retailer, or restaurant that didn't accept your card. But I'll bet that none of those places refused Visa. Its vast reach is to thank for that.
With the head start Visa has and its impressive growth rates, it's very unlikely one of its competitors will match that reach anytime in the foreseeable future. Add in the growing demand for electronic payments as the world progressively becomes more digital, and the company is in a good position to thrive over the long term.
You can't argue with its financials
In the second quarter of 2023, Visa made $8 billion in revenue, up 11% year over year. In its fiscal 2022, it made $29.3 billion, up 22% from the year prior. Its 2022 revenue got a boost from higher inflation (Visa takes a percentage of transactions, so higher transaction totals equal more revenue). And the company is a cash cow because of its high margins.
The company's large network didn't happen overnight; it's a by-product of lots of investment. But many of these investments were made years ago, so Visa now gets to reap the rewards with minimal added costs.
Few companies' margins are remotely comparable. The chart below shows how lucrative a position Visa is in with its industry and business model.
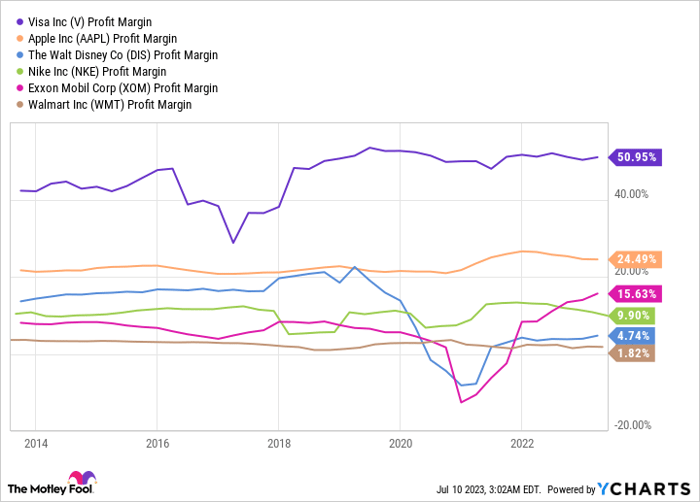
V Profit Margin data by YCharts
The stock isn't necessarily cheap
Shares have been impressive over the last decade, more than doubling the returns of the S&P 500. The stock has been lucrative for investors who have been along for the ride, but it could make prospective investors hesitant as it reaches levels many would consider expensive.
Its price-to-earnings ratio is 31.6; the S&P 500's is around 19.6, and American Express and Discover are about 17.8 and 7.8, respectively.
However, when it comes to Visa, I view it through the lens of whether you would feel comfortable holding it for the next 20 years. And the answer is yes. It might not be cheap, but I'm confident it has the long-term growth potential to warrant its valuation.
If you're worried about current prices, consider dollar-cost averaging your way into a stake instead of investing a lump sum.
10 stocks we like better than Visa
When our analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Visa wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of July 3, 2023
Discover Financial Services is an advertising partner of The Ascent, a Motley Fool company. American Express is an advertising partner of The Ascent, a Motley Fool company. Stefon Walters has positions in Apple. The Motley Fool has positions in and recommends Apple, Nike, Visa, Walmart, and Walt Disney. The Motley Fool recommends Discover Financial Services and recommends the following options: long January 2024 $145 calls on Walt Disney, long January 2025 $47.50 calls on Nike, and short January 2024 $155 calls on Walt Disney. The Motley Fool has a disclosure policy.
