
Is Advanced Micro Devices (NASDAQ:AMD) Using Too Much Debt?
David Iben put it well when he said, 'Volatility is not a risk we care about. What we care about is avoiding the permanent loss of capital.' When we think about how risky a company is, we always like to look at its use of debt, since debt overload can lead to ruin. We can see that Advanced Micro Devices, Inc. (NASDAQ:AMD) does use debt in its business. But is this debt a concern to shareholders?
What Risk Does Debt Bring?
Generally speaking, debt only becomes a real problem when a company can't easily pay it off, either by raising capital or with its own cash flow. If things get really bad, the lenders can take control of the business. However, a more common (but still painful) scenario is that it has to raise new equity capital at a low price, thus permanently diluting shareholders. Of course, debt can be an important tool in businesses, particularly capital heavy businesses. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
What Is Advanced Micro Devices's Debt?
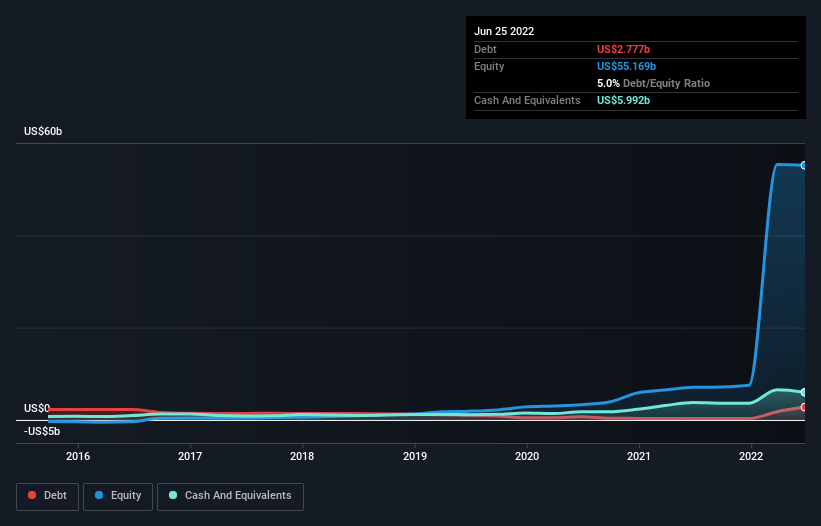
As you can see below, at the end of June 2022, Advanced Micro Devices had US$2.78b of debt, up from US$313.0m a year ago. Click the image for more detail. But on the other hand it also has US$5.99b in cash, leading to a US$3.22b net cash position.
How Strong Is Advanced Micro Devices' Balance Sheet?
We can see from the most recent balance sheet that Advanced Micro Devices had liabilities of US$5.52b falling due within a year, and liabilities of US$6.81b due beyond that. On the other hand, it had cash of US$5.99b and US$4.05b worth of receivables due within a year. So its liabilities outweigh the sum of its cash and (near-term) receivables by US$2.29b.
This state of affairs indicates that Advanced Micro Devices' balance sheet looks quite solid, as its total liabilities are just about equal to its liquid assets. So it's very unlikely that the US$165.2b company is short on cash, but still worth keeping an eye on the balance sheet. Despite its noteworthy liabilities, Advanced Micro Devices boasts net cash, so it's fair to say it does not have a heavy debt load!
On top of that, Advanced Micro Devices grew its EBIT by 45% over the last twelve months, and that growth will make it easier to handle its debt. There's no doubt that we learn most about debt from the balance sheet. But ultimately the future profitability of the business will decide if Advanced Micro Devices can strengthen its balance sheet over time. So if you're focused on the future you can check out this free report showing analyst profit forecasts.
Finally, a business needs free cash flow to pay off debt; accounting profits just don't cut it. While Advanced Micro Devices has net cash on its balance sheet, it's still worth taking a look at its ability to convert earnings before interest and tax (EBIT) to free cash flow, to help us understand how quickly it is building (or eroding) that cash balance. During the last three years, Advanced Micro Devices generated free cash flow amounting to a very robust 91% of its EBIT, more than we'd expect. That positions it well to pay down debt if desirable to do so.
Summing Up
We could understand if investors are concerned about Advanced Micro Devices's liabilities, but we can be reassured by the fact it has has net cash of US$3.22b. The cherry on top was that in converted 91% of that EBIT to free cash flow, bringing in US$3.3b. So is Advanced Micro Devices's debt a risk? It doesn't seem so to us. There's no doubt that we learn most about debt from the balance sheet. However, not all investment risk resides within the balance sheet - far from it. We've identified 2 warning signs with Advanced Micro Devices , and understanding them should be part of your investment process.
If you're interested in investing in businesses that can grow profits without the burden of debt, then check out this free list of growing businesses that have net cash on the balance sheet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
