
Garmin Stock: Bear vs. Bull
Wall Street was happy with the latest operating update from Garmin (NYSE: GRMN). Sure, the tech device company reported declining sales in late 2022 while projecting another year of weaker margins ahead. But Garmin performed well given all the pressures on its industry late last year.
The company has a packed pipeline of new product introductions across key niches like smartwatches and aviation navigation platforms, too.
With those contrasts in mind, let's look at the key bullish and bearish arguments for 2023 and beyond.
The bear case
Bears can point to several deteriorating metrics to support their arguments. In 2022, the company posted a second consecutive year of declining profit margin, and executives projected a third straight drop for 2023.
Garmin's long streak of solid sales growth ended last year, too. After six consecutive years of growth, revenue fell 2% to $4.9 billion. The worst segment was the fitness division, too, which had been its single largest unit heading into the year. That segment shrank by 27% in the fourth quarter and for the full fiscal year as consumer interest in fitness trackers fell.
Things aren't likely to improve by much in 2023, either. Along with that profit-margin drop, Garmin is forecasting revenue growth of just 3% this year. Achieving that result would put the sales footprint about where it was sitting two years earlier, at the end of 2021.
The bull case
Still, Garmin should get credit for posting such a modest sales drop in 2022 even as its biggest sales division slumped.
The company grew its smartwatch sales and posted solid gains in both its aviation and marine navigation divisions. These wins illustrate how Garmin's deep portfolio protects its growth rate even as parts of the business shrink.
And Garmin remains highly profitable. The 20% operating profit margin that management is projecting for 2023 isn't far from Apple's (NASDAQ: AAPL) industry-leading results. And the tech titan's profit margins fell in recent quarters, too, reinforcing the fact that Garmin's struggles were part of a wider pattern among tech manufacturers.
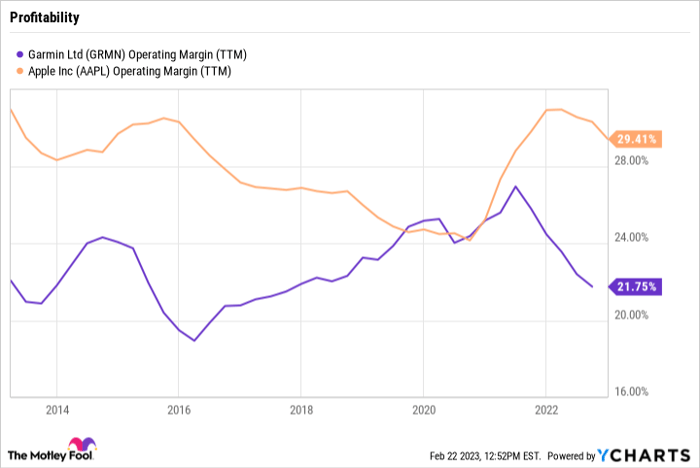
GRMN operating margin (TTM) data by YCharts. TTM = trailing 12 months.
The company's track record leading up to 2022 supports that bullish reading, as sales and earnings rose consistently with the company introducing a steady stream of new products across its targeted niches.
Looking ahead
That pace of launches will speed up in 2023, management says. The packed pipeline should help Garmin again avoid any large sales slump even if pockets of the business contract. But investors should be more excited about the long-term potential for this stock.
Once the temporary demand and cost challenges subside, Garmin is likely to return to its more-normal operating cadence, which had been annual growth in the high single digits. And operating profit margin has room to begin moving back up toward 25% of sales with new introductions in areas like aviation and specialty smartwatches. Apple's recent entry in the ultra-premium segment confirms the attractiveness of that niche, after all.
Altogether, there's a good chance that Garmin will be generating far more than $5 billion of annual revenue in a decade, along with more impressive earnings per share. Given that the stock's valuation has slumped since late 2021, success on these scores would likely deliver excellent returns for patient growth-stock investors.
10 stocks we like better than Garmin
When our award-winning analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Garmin wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of February 8, 2023
Demitri Kalogeropoulos has positions in Apple. The Motley Fool has positions in and recommends Apple and Garmin. The Motley Fool recommends the following options: long March 2023 $120 calls on Apple and short March 2023 $130 calls on Apple. The Motley Fool has a disclosure policy.
