
Forget Amazon, This Stock Is a Better Buy
You can't exactly forget Amazon. Some 200 million people are Prime members, and millions more still purchase from the e-commerce behemoth, or at least see the Prime truck rolling down their streets daily. As for its stock, I wouldn't strike it down right now either, and there are reasons to be bullish on Amazon shares.
But if you're looking for a great e-commerce growth stock and have a bit of an appetite for risk, there are other options that could supercharge your portfolio and offer the early-stage gains that Amazon created for shareholders when it was a younger company. Consider Global-e Online (NASDAQ: GLBE), which you may not have heard of, but which is demonstrating impressive growth.
Global e-commerce for all
Global-e operates an e-commerce platform that offers cross-border solutions for retailers. It has all kinds of packages and services geared toward enterprise and small businesses, allowing any retailer with a web site to ship globally. It offers localized checkout in about 100 currencies and 200 locations, taking care of customs calculations and providing multiple shipping options.
The company has a largely upscale client base, and in addition to helping small businesses expand their presence globally, it continues to gain large clients as well. In the 2023 third quarter, it added fashion brands Tory Burch and U.K.-based Ted Baker. It also added several new brands from its relationship with European fashion powerhouse LVMH, as well as electronics maker Bang & Olufsen.
Global-e also has an important partnership with Shopify, and it recently rolled out a new integration with Shopify Markets Pro for merchants to use the Global-e platform for cross-border e-commerce. There are already thousands of Shopify merchants on the platform, which officially launched in September, but Global-e expects it to start ramping up in the (current) fourth quarter.
Inflation is finally catching up
Global-e is still crushing it in sales growth, but it's beginning to feel the pinch of inflation. Revenue in its third quarter increased 27% year over year to $133.6 million, which was a big slowdown from the high double digits it has previously reported. It was also below its own guidance as well as analyst expectations, and management lowered full-year revenue guidance. It had guided for about $139 million, and analysts were expecting $142 million.
The company attributed this revenue miss mostly to a slowdown in the European luxury market. Luxury sales account for around 30% of total gross merchandise volume (GMV), while the European market accounts for 30% of total GMV.
Management said these trends look like they're reversing, and it sees better times ahead for 2024. But it did revise its 2023 full-year sales guidance from about $583 million to $567 million.
Why the future looks bright
Profitability continues to improve as the company benefits from economies of scale as well as rigorous cost efficiency. Adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) increased 76% over last year to $22.1 million, coming in on top of the high end of guidance. The adjusted EBITDA margin was 16.5%, up from 11.9% last year.
Management raised the full-year outlook from about $89 million to around $92 million. Net loss improved from $65 million to $33 million, and loss per share of $0.21 was better than Wall Street's expectation of $0.26.
Global-e has a large funnel of new clients that it regularly onboards, and it's also expanding current partnerships to added services and new markets. It specifically expects the ramp-up of the Shopify Markets Pro program to add significant value to its business.
It also just announced a partnership with web site creator Wix for users to add an integration to retail web sites. Although this is a smaller endeavor, management said it expects it to add incremental value to Global-e's business.
Is Global-e stock a better buy than Amazon?
Investors were disappointed with Global-e's revenue miss and revision, and its stock fell 27% in one day after the report was released.
Global-e stock isn't cheap, and although a premium could be justified for its high growth, investors won't give it such a premium at these lower growth rates. When the valuation is very high, there isn't much room for error; when there is error, the price will fall.
At the current price, Global-e stock still trades at an expensive price-to-sales ratio of 9.4 versus 2.7 for Amazon. However, Global-e stock trades at a significant discount to its lifetime average, whereas Amazon stock is trading near its average over the same time period.
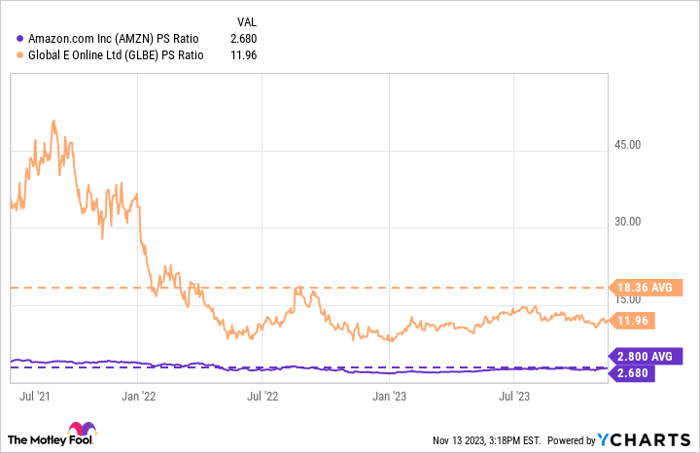
AMZN PS Ratio data by YCharts
Global-e has plenty of growth drivers, and business should reaccelerate under better conditions. It's also moving closer to profitability. This looks like a great opportunity for investors to grab shares on the dip.
10 stocks we like better than Global-e Online
When our analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Global-e Online wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of November 15, 2023
John Mackey, former CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool's board of directors. Jennifer Saibil has positions in Global-e Online. The Motley Fool has positions in and recommends Amazon, Global-e Online, Shopify, and Wix.com. The Motley Fool has a disclosure policy.
