
Does Netflix Have a Cash Problem?
Streaming giant Netflix (NASDAQ: NFLX) has grown for years to become a titan in the entertainment industry with more than 221 million subscribers worldwide. The stock has been similarly successful, returning more than 2,200% in just the past decade.
However, Netflix has steadily transformed its business over the years, transitioning from licensed third-party content to in-house productions it owns. That strategy has largely paid off with a large and growing library of originals, but the financial side of the business seems to be hitting some bumps.
Let's break down Netflix's cash-flow dilemma and discuss what challenges it could create for the company in this environment of rising interest rates.
Image source: Getty Images.
More content, more spending
Netflix has been ratcheting up its in-house content development for years, and it's done a great job if its 27 Oscar nominations at the 94th Academy Awards mean anything.
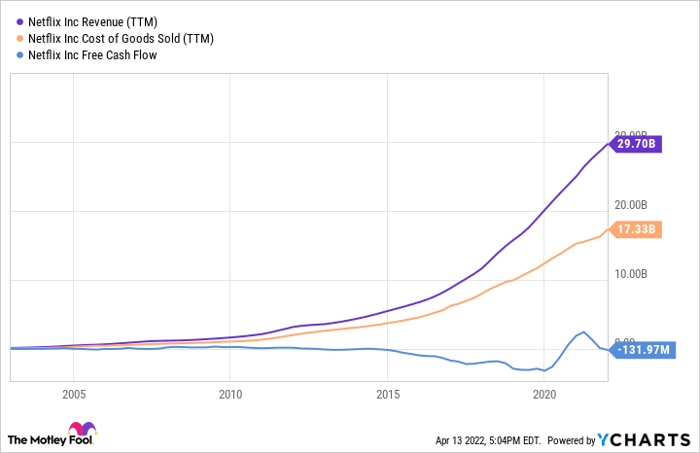
Below, you can see how the company's cost of goods sold, which captures its content spending, has grown along with revenue. The business is very profitable -- net income in 2021 totaled $5.1 billion. However, that's because of how the company amortizes its content spending. If you look at the company's free cash flow, it paints a much different picture.
Data by YCharts.
The business is actually burning cash most years, despite the strong profits on its income statement. Netflix borrows money to help fund content, and it currently has a net debt (total debt minus cash) balance of $9.4 billion.
Could rising rates hurt Netflix?
This could potentially put Netflix in a bind -- rising interest rates due to high inflation will likely make borrowing more expensive. The ideal solution is Netflix growing revenue faster than its expenses, which also comes with a Catch-22.
In recent years, streaming has become increasingly competitive. Virtually every major content developer launched services just in the past few years. Some of these companies, like Walt Disney, have decades of legacy content built up, which has enabled them to fill their content catalog without breaking the bank.
Netflix's premium plan costs $19.99 per month in the U.S., and it's worth wondering how much more it can increase pricing without spiking its churn rates. Netflix has been a staple in many streaming households for so long that it may have the pricing power it needs, but I wouldn't assume that as a sure thing.
What's the "end game"?
Perhaps more importantly, what's the long-term investment thesis for Netflix? In recent years, subscriber growth has slowed notably with management guiding for the company's fourth consecutive quarter of single-digit year-over-year subscriber growth in the first quarter of 2022.
If subscriber growth doesn't pick back up, it could pressure Netflix to further raise its prices. It's unlikely the company's content spending will shrink anytime soon. Great content has replay value, but there will be a constant need to invest in new hit shows and movies to keep the competition at bay.
I'm not trying to say that Netflix is in financial trouble, but free cash flow is important as businesses mature. It funds dividends and share repurchases, which investors look for as revenue growth slows. If Netflix can't deliver on that metric, I worry the stock may hit a long-term "glass ceiling." It's something investors will need to watch for over the coming quarters and years.
10 stocks we like better than Netflix
When our award-winning analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Netflix wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of April 7, 2022
Justin Pope has no position in any of the stocks mentioned. The Motley Fool owns and recommends Netflix and Walt Disney. The Motley Fool recommends the following options: long January 2024 $145 calls on Walt Disney and short January 2024 $155 calls on Walt Disney. The Motley Fool has a disclosure policy.
