
Disney Stock: Bull vs. Bear
On the surface, Walt Disney (NYSE: DIS) stock stands out as an incredible buy, on sale for 33% off its 52-week high. But buying a stock just because its price is lower is usually a great way to get in trouble.
When building an investment case, it can be useful to play devil's advocate by poking holes through your own arguments. As Charlie Munger famously has said, "Invert, always invert. Turn a situation or problem upside down. Look at it backward."
So let's discuss the bear and bull cases on the media stock now to see if the discount on Disney stock is as appealing as it looks.
Image source: The Walt Disney Company.
The bear case
The bear case against Disney is compelling and has real red flags that investors should consider. Through that bearish lens, you could argue that Disney+ faces an uphill battle -- and not just against other streaming players like Netflix (NASDAQ: NFLX), Amazon, Apple, and HBO Max, but also media in general, whether that's YouTube, video games, TikTok, or social media.
Disney's investments in Disney+ could be better spent on its parks or movie business -- which have high operating margins and a proven track record, and so they are arguably a better use of capital. And even those businesses could face challenges in the short-term in the form of pricing pressure in an inflationary environment.
What's more, Disney stock doesn't pay a dividend. And management has shown little to no interest in reinstating the dividend anytime soon. Despite a blowout quarter, the company is generating a fraction of the profit it used to due to high spending and a business that is still rebounding from the pandemic.
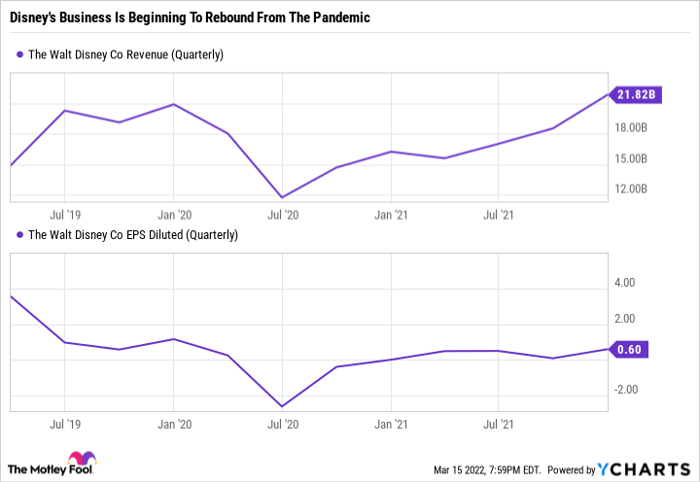
DIS Revenue (Quarterly) data by YCharts
The parks may be opening again. But Disney+ still must achieve long-term profitability for it to be a success. In addition to this underlying uncertainty, it's unclear how much of the surge in park performance is due to pent-up demand for vacations. As the COVID-19 situation improves, Disney needs to show that it can keep growing its park performance by, for instance, attracting repeat business from avid park goers. Deprived vacationers may be willing to accept Disney's price hikes and the added cost of Genie+ and Lightning Lane. But it remains to be seen if these added costs will be sticky over the long term.
The bull case
The problem with most of the bearish points is that they are short-term problems. Disney is a powerful global brand and a media machine that isn't going away anytime soon.
Disney's parks have exhibited impeccable pricing power even during times of inflation. For example, Disney noted that per capita spending at domestic parks increased by 40% in Q1 of fiscal 2022 compared to Q1 of fiscal 2019 -- a sign that customers are shrugging off Disney's price hikes.
What's more, Disney+ has a far richer legacy content portfolio than newer pure-play streaming services. The value of hit Disney movies doesn't end at the box office, but rather has a longer shelf life because they can be added to Disney+, generate revenue from merchandise, and even provide the inspiration for theme park rides and attractions. Unlike other streaming providers that desperately have to spend more money on content to keep subscribers entertained to justify price hikes, Disney has a much more efficient and lasting business model.
Disney+ is worth investing in because it could provide the first touchpoints for lifelong Disney customers. The lifecycle of a Disney customer tends to begin during childhood from someone that grew up with Disney, maybe went to the parks or played with the toys, watches the movies, and then passes along that joy to their kids. Disney+ hosts decades of high-quality content, and is home to new content that adds value to the worlds that Disney characters live in. Therefore, Disney+ seamlessly integrates into Disney's overall content portfolio and could very well boost engagement at its parks and movies over time as consumers become more involved in various Disney universes like Star Wars and Marvel.
Where to go from here
Stock prices ping pong up and down because investors have different ideas of what a company is worth. Yet most of the short-term price movement can be far removed from the long-term investment thesis.
When I look at Disney's business today and its trajectory vs. Disney's business three or five years ago, I see a company that is only getting better. I see a company with a much more sustainable and diversified business model than, say, Netflix. I see a business that is developing characters, making memories, and providing so many different entertainment outlets on and off-screen. These green flags far outweigh short-term red flags regarding Disney's lower profits and lack of a dividend.
But I also understand that some investors may prefer waiting awhile to make sure Disney+ amounts to everything Disney hopes it will become before hitting the buy button.
10 stocks we like better than Walt Disney
When our award-winning analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Walt Disney wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of March 3, 2022
John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool's board of directors. Daniel Foelber owns Walt Disney and has the following options: long January 2024 $145 calls on Walt Disney, long July 2022 $145 calls on Walt Disney, long June 2022 $170 calls on Walt Disney, long March 2022 $155 calls on Walt Disney, short January 2024 $150 calls on Walt Disney, short July 2022 $150 calls on Walt Disney, short June 2022 $175 calls on Walt Disney, short March 2022 $140 calls on Walt Disney, and short March 2022 $160 calls on Walt Disney. The Motley Fool owns and recommends Amazon, Apple, Netflix, and Walt Disney. The Motley Fool recommends the following options: long January 2024 $145 calls on Walt Disney, long March 2023 $120 calls on Apple, short January 2024 $155 calls on Walt Disney, and short March 2023 $130 calls on Apple. The Motley Fool has a disclosure policy.
