
CRDO Down 20.3% in a Month: Is the Weakness an Opportunity?
Credo Technology Group Holding Ltd CRDO has fallen 20.3% in the past month even as its AI-infrastructure connectivity business continues to expand at a rapid pace.
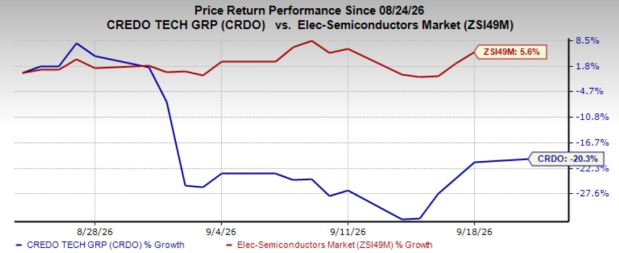
Image Source: Zacks Investment Research
The pullback lowers the share price, but it does not remove the valuation, customer concentration and execution risks surrounding the next phase of growth. The question is whether operating momentum can keep pace with expectations.
CRDO’s Selloff Contrasts With Triple-Digit Growth
Fiscal first-quarter 2027 revenues rose 114.7% year over year to $479 million. That marked Credo’s seventh consecutive quarter of triple-digit year-over-year revenue growth and a 9.6% sequential increase.
Credo Technology Group Holding Ltd. Revenue (Quarterly)

Credo Technology Group Holding Ltd. revenue-quarterly | Credo Technology Group Holding Ltd. Quote
Non-GAAP net income reached $236.3 million, while non-GAAP operating margin was 48.2%. Management also expects fiscal 2027 revenues to grow more than 85%, keeping the earnings story tied to continued scale.
Credo’s AEC Engine Still Leads the Expansion
Active electrical cables (AECs) remained Credo’s largest business unit in the fiscal first quarter. Growth reflects deeper penetration at hyperscale customers, relationships with five hyperscalers and expanding adoption among NeoCloud providers.
The shift toward 200-gig-per-lane connectivity creates another layer of demand. Credo expects 1.6T AECs to begin contributing in the second half of fiscal 2027 and ramp more broadly in fiscal 2028. Astera Labs, Inc. ALAB also reported 104% year-over-year revenue growth in second-quarter 2026 as AI fabrics and signal conditioning expanded.
CRDO’s Optical Ramp Adds a Second Growth Engine
Credo expects more than $600 million in fiscal 2027 optical revenues. ZeroFlap optics, silicon photonics PICs and optical DSPs are each projected to contribute more than $100 million.
Initial silicon photonics revenues have begun after the DustPhotonics acquisition, with wins at 800G and 1.6T. ZeroFlap optics are already in production shipments, while first 1.6T digital signal processor revenues are expected later in fiscal 2027. Marvell Technology, Inc. MRVL reported 46% year-over-year data-center revenue growth in fiscal second-quarter 2027, including strong demand in connectivity.
Credo’s Concentration Risk Could Keep Pressure High
The four largest end customers generated 33%, 28%, 13% and 10% of first-quarter fiscal 2027 revenues. The top two alone accounted for 61%, leaving results sensitive to changes in deployment schedules at a small number of buyers.
Costs can add another source of variability. GAAP research and development expense rose 118% year over year to $114.5 million, while management expects non-GAAP operating expenses to rise about 55% in fiscal 2027. The outlook also assumes a tariff regime that management described as fluid.
CRDO’s Valuation Still Demands Strong Execution
CRDO trades at 11.1X forward 12-month sales, compared with 5.0X for its Zacks sub-industry and 6.1X for the broader Zacks sector. Its five-year median is 12.2X.

Image Source: Zacks Investment Research
The pullback has moved the multiple below that historical median, but the premium to the sub-industry and sector remains substantial. Continued execution across AECs, optics and newer connectivity products is therefore important to supporting the current valuation.
Credo’s Mixed Signals Frame the Setup
The 20.3% decline improves the entry price, but CRDO still carries a premium valuation and meaningful concentration risk. Rapid revenue growth and a broader connectivity portfolio provide offsets, leaving the setup more balanced than the share-price decline alone suggests.
CRDO currently carries a Zacks Rank #3 (Hold), with a Growth Score of B, Momentum Score of B, Value Score of D and VGM Score of C. The B readings are favorable for growth and momentum characteristics, while the D Value Score is weaker and the C VGM Score sits in the middle of the grading scale. Because Style Scores complement the Zacks Rank, the signals do not point in one direction.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpCredo Technology Group Holding Ltd. (CRDO) : Free Stock Analysis Report
Marvell Technology, Inc. (MRVL) : Free Stock Analysis Report
Astera Labs, Inc. (ALAB) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
