
Can AMD Compete in the AI Revolution?
Advanced Micro Devices (NASDAQ: AMD) stock has been a fantastic investment over the past five years, as the stock has risen nearly 700%. Much of this return dealt with AMD launching competitive products and getting its finances in check. Now that that transition is over, AMD investors are looking toward a new catalyst to drive the stock higher: artificial intelligence (AI).
While AMD isn't directly competing in this space against massive names like OpenAI, it's products are heavily utilized in AI applications, including training, development, and implementation, making AMD a "picks and shovels" type of investment. Because of that, it will benefit significantly from AI proliferation. However, AMD's latest results don't reflect this theory, and it could be a useful warning signal for AI-focused investors.
AMD has a crucial component in the AI supply chain
AMD has multiple business segments, including data center, client, gaming, and embedded revenue. The data center division is the key area to focus on when trying to discern whether AI is making a difference in AMD's finances. Within its product lines are central processing units (CPUs), graphics processing units (GPUs), and data processing units (DPUs), each a vital piece of equipment when building a data center meant for AI training and implementation.
If the AI revolution was occurring at lightspeed, its data center revenue stream would see a significant spike in business. However, in the first quarter, data center revenue was flat year over year. Management commented that the division saw higher cloud sales but lower enterprise sales -- something they expected. Still, they were happy with the partnerships that were made and noted that declining enterprise sales were caused by economic uncertainty.
Management also discussed accelerating its AI strategy in Q1 and named AI its "No. 1" strategic priority through various product launches, like the AMD Instinct MI300, which can cut down on the time needed to train an AI model. This new product offers eight times the performance over AMD's current MI250X offering, and is a significant development in the AI field.
With AI in the early innings, there is still a lot of room for development to happen. This is why investors shouldn't panic if they don't see a sales spike immediately.
But what's happening in AMD's other segments may be concerning.
AMD's other segments performed terribly in Q1
Looking at AMD's other segments reveals some severe weaknesses. Its client revenue fell 65% year over year due to a weak PC market. However, gaming wasn't nearly as weak, with revenue only falling 6%. Finally, embedded revenue increased 163% year over year. That isn't a fair comparison, since this quarter includes a full quarter of Xilinx revenue (AMD's recent embedded processor acquisition), whereas Q1 2022 only had partial Xilinx revenue.
Altogether, AMD's revenue fell 9% from last year and posted a $0.09 per share loss in Q1. That's not a good showing for a company with a massive catalyst like AI on the horizon, but it also demonstrates that AI is a long-term movement, not an immediate one. It's not expected to improve either, as Wall Street analysts project revenue falling 11.6% in 2023. However, they also predict AMD's revenue to rise by 17.6% in 2024, making right now an intriguing time to take a position in the stock.
At its current valuation, AMD is much cheaper than it has been in a while.
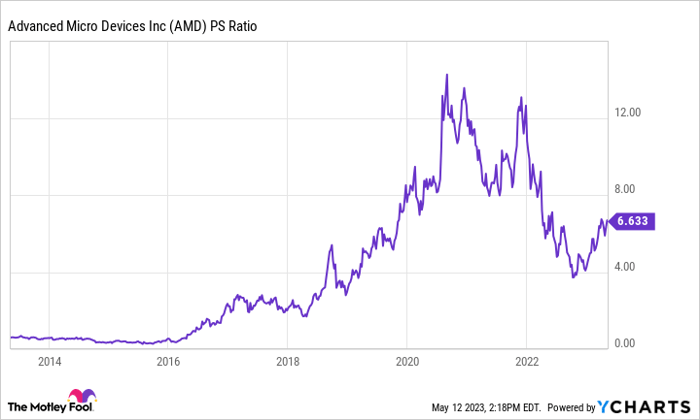
AMD PS Ratio data by YCharts
It's also much cheaper than competitor Nvidia (NASDAQ: NVDA), a stock that trades for 26 times sales. Still, it's well above the levels AMD traded at before its massive run-up, which could be a warning sign.
However, with the AI catalyst on the horizon, AMD still has bright days ahead. While the stock isn't as cheap as it used to be, AMD is worth owning if you're willing to hold on to it for three to five years. The AI revolution won't happen overnight, but stock market-moving headlines will. If you focus on the long term, AMD will likely be a strong investment if AI technology changes as much as most investors think it will. If AI falls on its face, AMD will still be a decent investment, as data centers, PCs, and gaming will all remain relevant industries.
10 stocks we like better than Advanced Micro Devices
When our analyst team has a stock tip, it can pay to listen. After all, the newsletter they have run for over a decade, Motley Fool Stock Advisor, has tripled the market.*
They just revealed what they believe are the ten best stocks for investors to buy right now... and Advanced Micro Devices wasn't one of them! That's right -- they think these 10 stocks are even better buys.
*Stock Advisor returns as of May 8, 2023
Keithen Drury has positions in Nvidia. The Motley Fool has positions in and recommends Advanced Micro Devices and Nvidia. The Motley Fool has a disclosure policy.
